
The Auto Cave Photos


You might also consider


More like The Auto Cave
Recommended Reviews - The Auto Cave
Start your review...

Reviews With Photos

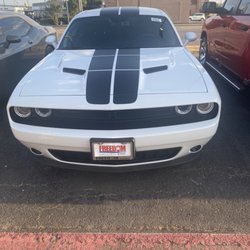
Bought a camaro. Had to go back for work not even a full 2 weeks later. Had to rebuild trans and all although at no cost financially but costed alot of time. Went to pick up the vehicle finally after still paying while it was being serviced for something that was broken when i bought it. after the service center delays made me lose my job. after i called and requested the car to be out in case i dont make it In time before the "service" department closes. And to no surprise the cars not out and i wasted a $50 fees for that ride there and Also was told off by the lady manager that "its my fault im sitting here begging for a car" plus more. This is after i put $7K+ down for this car. And just paid 640 the morning same before I came to the place. No response from a supervisor only measly managers. had to google owner to email and hope this place gets corrected.


1 year ago
5 days ago
5 months ago
5 months ago
1 year ago
1 year ago
1 year ago
1 year ago
1 year ago
2 years ago
2 years ago
2 years ago

4 years ago
5 years ago
Bought a camaro. Had to go back for work not even a full 2 weeks later. Had to rebuild trans and all although at no cost financially but costed alot of time. Went to pick up the vehicle finally after still paying while it was being serviced for something that was broken when i bought it. after the service center delays made me lose my job. after i called and requested the car to be out in case i dont make it In time before the "service" department closes. And to no surprise the cars not out and i wasted a $50 fees for that ride there and Also was told off by the lady manager that "its my fault im sitting here begging for a car" plus more. This is after i put $7K+ down for this car. And just paid 640 the morning same before I came to the place. No response from a supervisor only measly managers. had to google owner to email and hope this place gets corrected. read more

3 years ago
3 years ago

5 years ago
5 years ago
5 years ago
Horrible service! My car got broke into while being serviced and them holding my car for 5 days inconveniencing me . When I went to pick it up they did not inform me that they had a break in I had to find out for myself getting in my car and it being trashed and several items missing and it smelling like mildew from them leaving my windows down . I'm so stressed out about this situation. It's been 2 days no one has reached out about my belongings and they did not file a police report but still charged my card to take my payment but they haven't helped me at all I missed work when they had my car for 5 days because they don't inform you of how long they will keep your car. I would advise anyone to take there business elsewhere. All they want is your money they don't care what you go through and you are not in good hands dealing with them. And it's crazy how they try to charge your card all day and call you all day but you can never get a answer when you need them! read more


5 years ago
4 years ago
More info about The Auto Cave
Ask the Community - The Auto Cave
You might also consider




Why does Yelp recommend reviews?
1 review that is not currently recommended
The reviews below are not factored into the business's overall star rating.
7 months ago


