
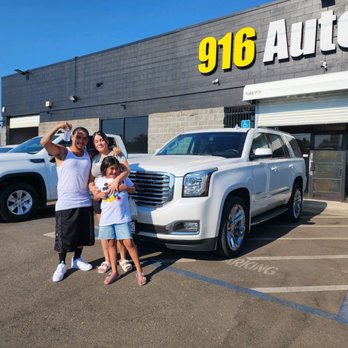
916 Auto Mart Photos


You might also consider


More like 916 Auto Mart
Recommended Reviews - 916 Auto Mart
Start your review...

Reviews With Photos

Owner was courteous and friendly like most professional sales people. When asking specific questions about car the owner stood by his shops review of vehicle components. I asked specific questions about tires and brakes and was assured the shop went through it and there were no outstanding issues. I simply explained we would drive over , take it for a test drive and be as quick as possible since we are busy. I told salesperson my main concern was buying a car that needed work or maintenance right away, and again I was assured everything was good. We arrived with notice and an understanding we were taking it for a test drive. The suv was behind 3 parked cars and not ready to be driven. The tires were bald (see attached picture). This was a deal breaker as I said I wanted a car ready to drive and was told everything was good. It was Not even worth checking other items I was told were "fine". This was a waste of my and my families time so we left.


I'm really baffled on how I was actually treated and helped at a car dealership. I never had an experience like this before. Usually you walk into the dealership and first thing they do is try to sell you on something and try to get over on you. But the gentleman that helped me actually helped me with my problem and help me look for what was suitable for my financial needs. It definitely was a different experience when the salesman actually try's to help instead of trying to sell all kinds of packages you don't need. I was stuck with a 2023 Honda Monkey that my friend used my credit to buy and ended up not paying the first payment. My salesperson got me close to what I paid for it and helped me drive away with the car that I can afford. I would definitely recommend and send all my family & friends here because they definitely earned my trust.


2 months ago
I had a great experience buying my 2016 Camaro 2SS from Tom at 916 Auto Mart. Tom was very helpful, straightforward, and easy to work with throughout the whole process. He was fair and reasonable when it came to negotiating the price, which I really appreciated. The whole experience was smooth and stress-free. I'm very happy with my purchase and would definitely recommend Tom and 916 Auto Mart to anyone looking for a vehicle. Great guy and great dealer! read more
15 days ago
3 months ago
7 months ago
Owner was courteous and friendly like most professional sales people. When asking specific questions about car the owner stood by his shops review of vehicle components. I asked specific questions about tires and brakes and was assured the shop went through it and there were no outstanding issues. I simply explained we would drive over , take it for a test drive and be as quick as possible since we are busy. I told salesperson my main concern was buying a car that needed work or maintenance right away, and again I was assured everything was good. We arrived with notice and an understanding we were taking it for a test drive. The suv was behind 3 parked cars and not ready to be driven. The tires were bald (see attached picture). This was a deal breaker as I said I wanted a car ready to drive and was told everything was good. It was Not even worth checking other items I was told were "fine". This was a waste of my and my families time so we left. read more


9 months ago

9 months ago

1 year ago

1 year ago
10 months ago
8 months ago
1 year ago
5 months ago

1 year ago

I'm really baffled on how I was actually treated and helped at a car dealership. I never had an experience like this before. Usually you walk into the dealership and first thing they do is try to sell you on something and try to get over on you. But the gentleman that helped me actually helped me with my problem and help me look for what was suitable for my financial needs. It definitely was a different experience when the salesman actually try's to help instead of trying to sell all kinds of packages you don't need. I was stuck with a 2023 Honda Monkey that my friend used my credit to buy and ended up not paying the first payment. My salesperson got me close to what I paid for it and helped me drive away with the car that I can afford. I would definitely recommend and send all my family & friends here because they definitely earned my trust. read more


Business owner information

Young H.
Thank you so much for sharing your incredible experience at 916 Auto…
1 year ago
1 year ago
1 year ago
1 year ago
2 years ago
1 year ago

6 years ago
I bought a car here at 916 Auto Mart, and little did I know, they sold me a LEMON. The 2016 Honda Civic LX they sold me had a busted Speedometer and Odometer. How do you like to drive a car with no Speedometer? I tried to have them fix the problem, but they did not want to deal with it. I had no choice but to leave the car with them, and I will report them to the California State Attorney General's Office for investigation. Consider yourself warned, "DO NOT BUY" cars in this shady dealer called 916 Auto Mart. read more


2 years ago
2 years ago
2 years ago
2 years ago
2 years ago

6 years ago
Business owner information
Young H.
We're happy to hear you found a great deal at 916 Auto Mart!…
2 years ago

6 years ago

5 years ago
3 years ago

5 years ago
Business owner information
Young H.
Thank you for sharing your experience! Our friendly and professional…

9 years ago
If your searching for a place to go to to waste your time and money, you've come to the right place! My husband and I stopped to look at vehicles an hour before they closed. The lady saleswoman (I guess that's what she is. She didn't have much conversation for us) was already moving cars into the garage to close down for the day. We were not acknowledged at all. She walked past us several times without a word. I would have taken it personal had she not already been ignoring another couple. We finally flagged her down to ask her about the Denali she told me about over the phone (at which time she told me she'd send me pictures of and never did). She said they wanted $16,900 for it! A 2007 Denali with 164,000 miles! I think she noticed the look of WTF on our faces because she said, "it's loaded! It's got everything." Unless "everything" is a trunk full of $100 bills, I think not. We then went in and saw a 2007 Ford Expedition. They wanted $13,995 for it, which was still a huge joke. But we thought we may be willing to bite the bullet to get the car for only "$399 down!" like they claim they offer. I asked if we could take the truck for a test drive. She told us, NO. What the what!? We had to be approved for the car FIRST before we were allowed to test drive! That should have been our cue to leave, but I insisted we complete the application. Went inside and filled out our application and handed it to some dude in the office. Another one of their rude employees who lack any kind of customer service skills. He barely looked up from his computer when we came in. No handshake, nothing. If this was the finance guy, he should finance himself a DRESS SHIRT, because he was wearing a sleeveless basketball jersey. Nothing says, "I don't GAF about your experience here" than wearing gym wear to work. He took our application and told us to go sit back down and watch television. By that time my husband was DONE with this place! About 10 minutes later, the rude lady comes back and says they need $4000 down on the Expedition. YEAH RIGHT! That truck isn't even worth THAT! Clearly the $399 down is for people with great credit; people who would never dream to come to this place anyway! If you qualified for $399 down here, you'd probably qualify to get a car less than 10 years old, with less than 150k miles and not 5x the blue book value. JUST like we left this place and went straight to John L. Sullivan in Yuba City and bought a 2015 with 35,000 miles, full factory warranty still in place, for $800 down. They deserve 0 stars! read more


7 years ago

6 years ago

8 years ago

6 years ago

6 years ago
Business owner information
Young H.
Thank you for considering us the best place to buy a used car in…

9 years ago
Business owner information
Young H.
Hi Teri, please give us a call. I do not recall this issue. Thank you.

7 years ago
Page 1 of 3
More info about 916 Auto Mart
Ask the Community - 916 Auto Mart
Review Highlights - 916 Auto Mart
You might also consider



Why does Yelp recommend reviews?
47 reviews that are not currently recommended
The reviews below are not factored into the business's overall star rating.
1 year ago
1 year ago

2 years ago
3 years ago
10 years ago
6 years ago

5 months ago

2 years ago

10 years ago
7 years ago
9 years ago
1 year ago

10 years ago

10 years ago
8 years ago
2 years ago

8 years ago

10 years ago
2 years ago

10 years ago


